F&B Services Index: August 2026 – Decline Narrows as Momentum Builds
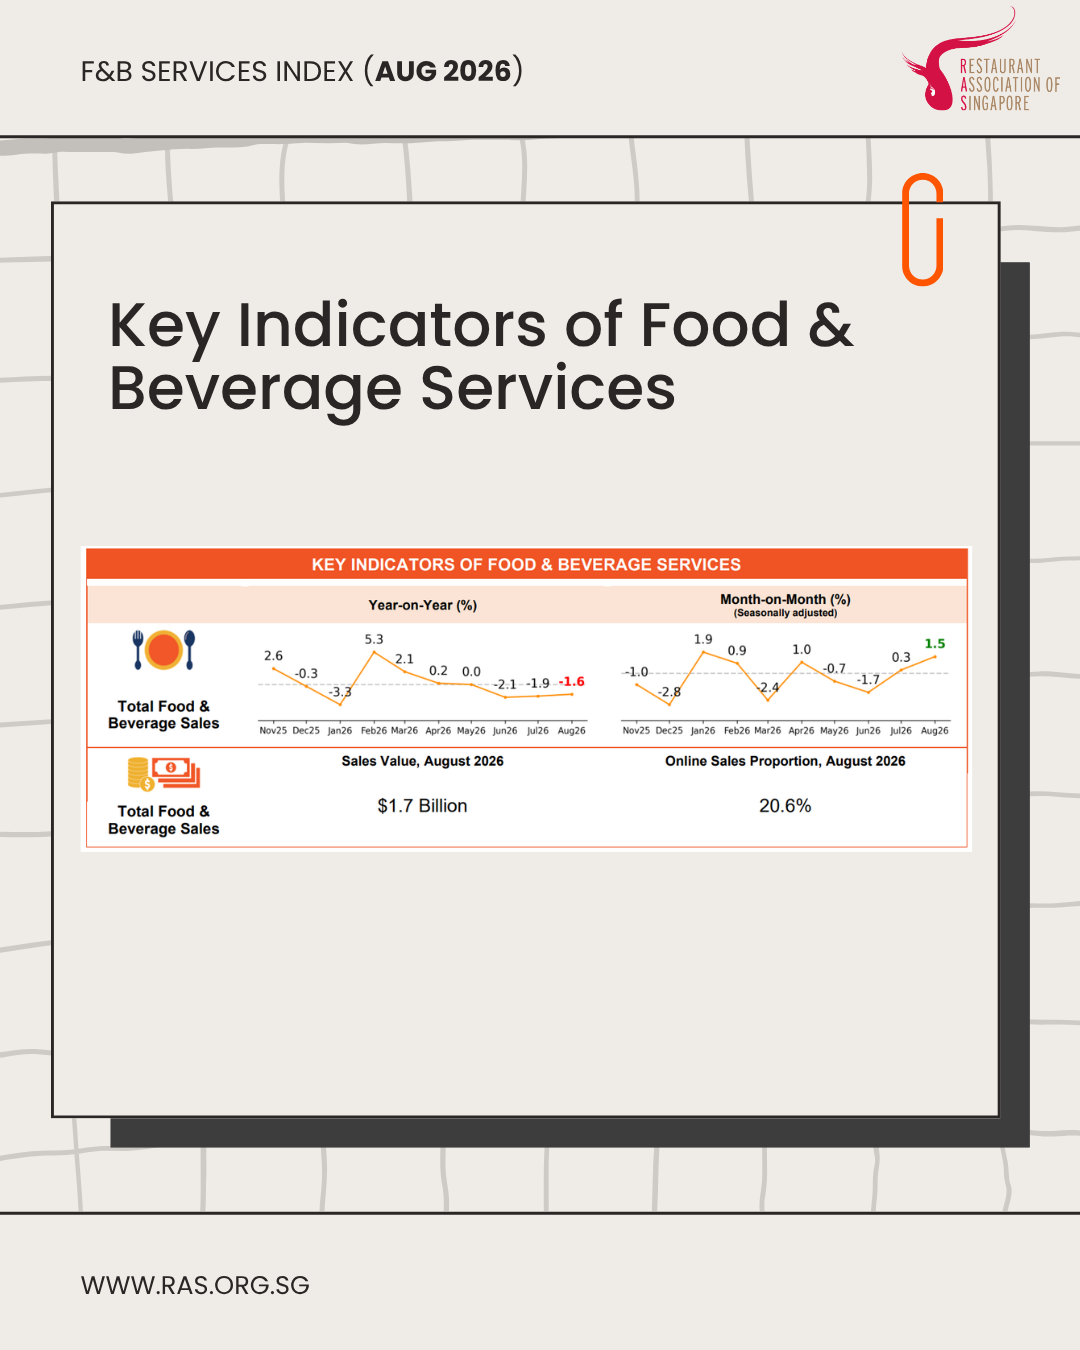
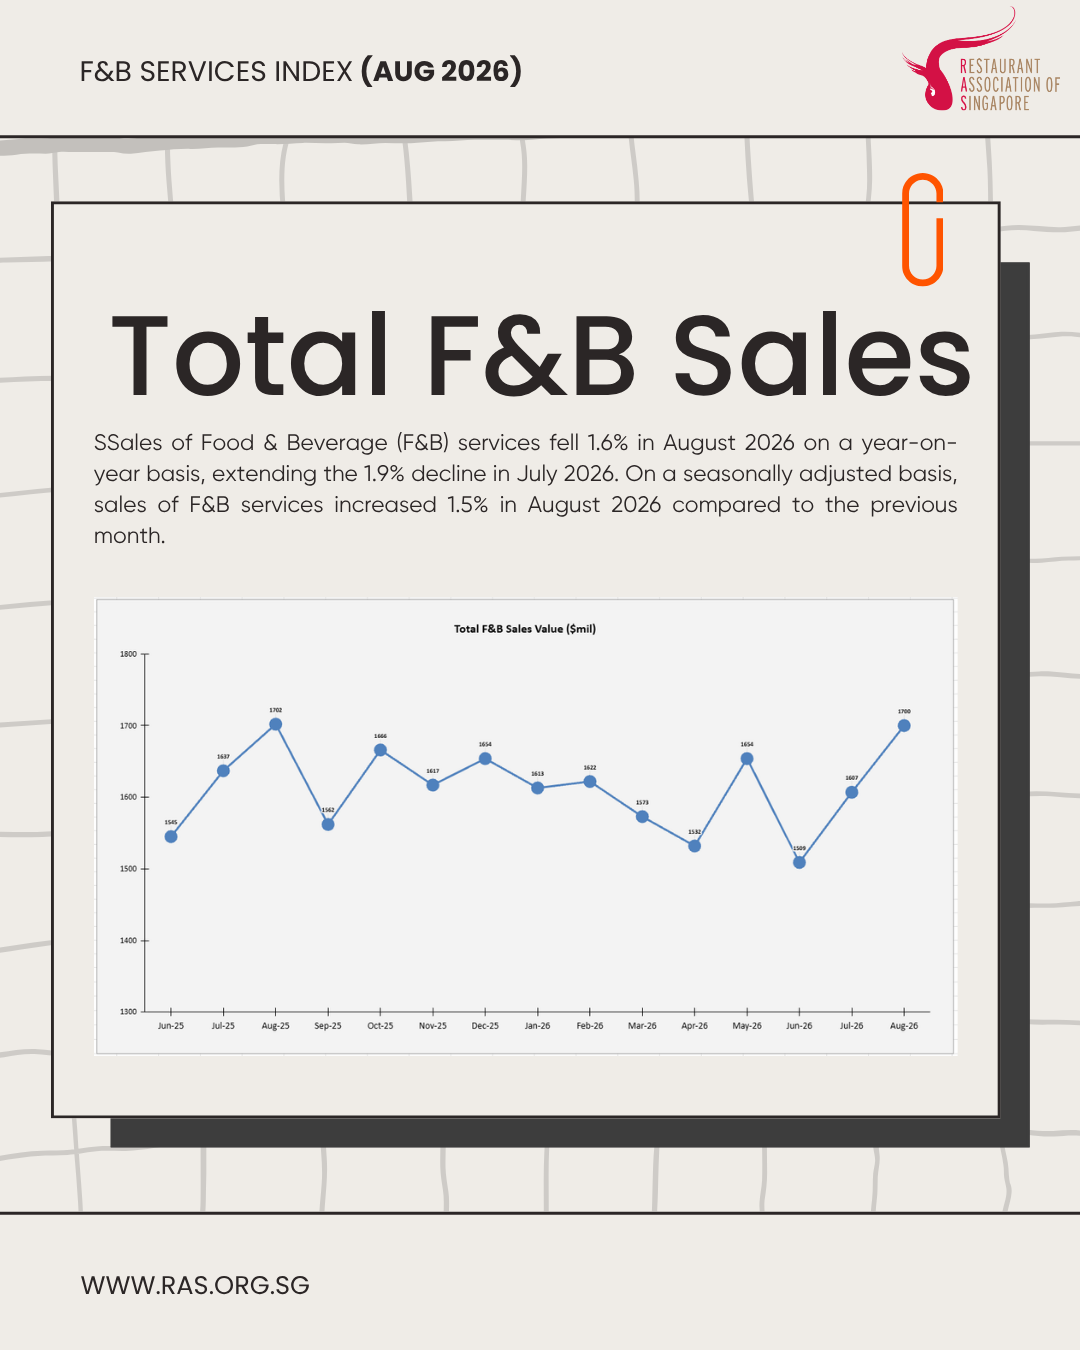
The latest Food & Beverage Services Index for August 2026, released by the Singapore Department of Statistics, shows a sector gradually finding its footing. F&B sales fell 1.6% year-on-year. That is a smaller decline than July's 1.9%, and the second month in a row that the gap has narrowed. Total sales reached an estimated $1.7 billion, up from $1.6 billion in July.
This is encouraging, but it is not yet a recovery. August is the third consecutive month in which F&B sales stayed below the previous year's levels. The improvement is also uneven across segments.
The Numbers: Momentum Picks Up
On a seasonally adjusted basis, F&B sales rose 1.5% from July. This is the sector's strongest month-on-month gain since January 2026. Every segment except Food Caterers grew over the month, which suggests the improvement is broad rather than driven by one category.
Segment by Segment
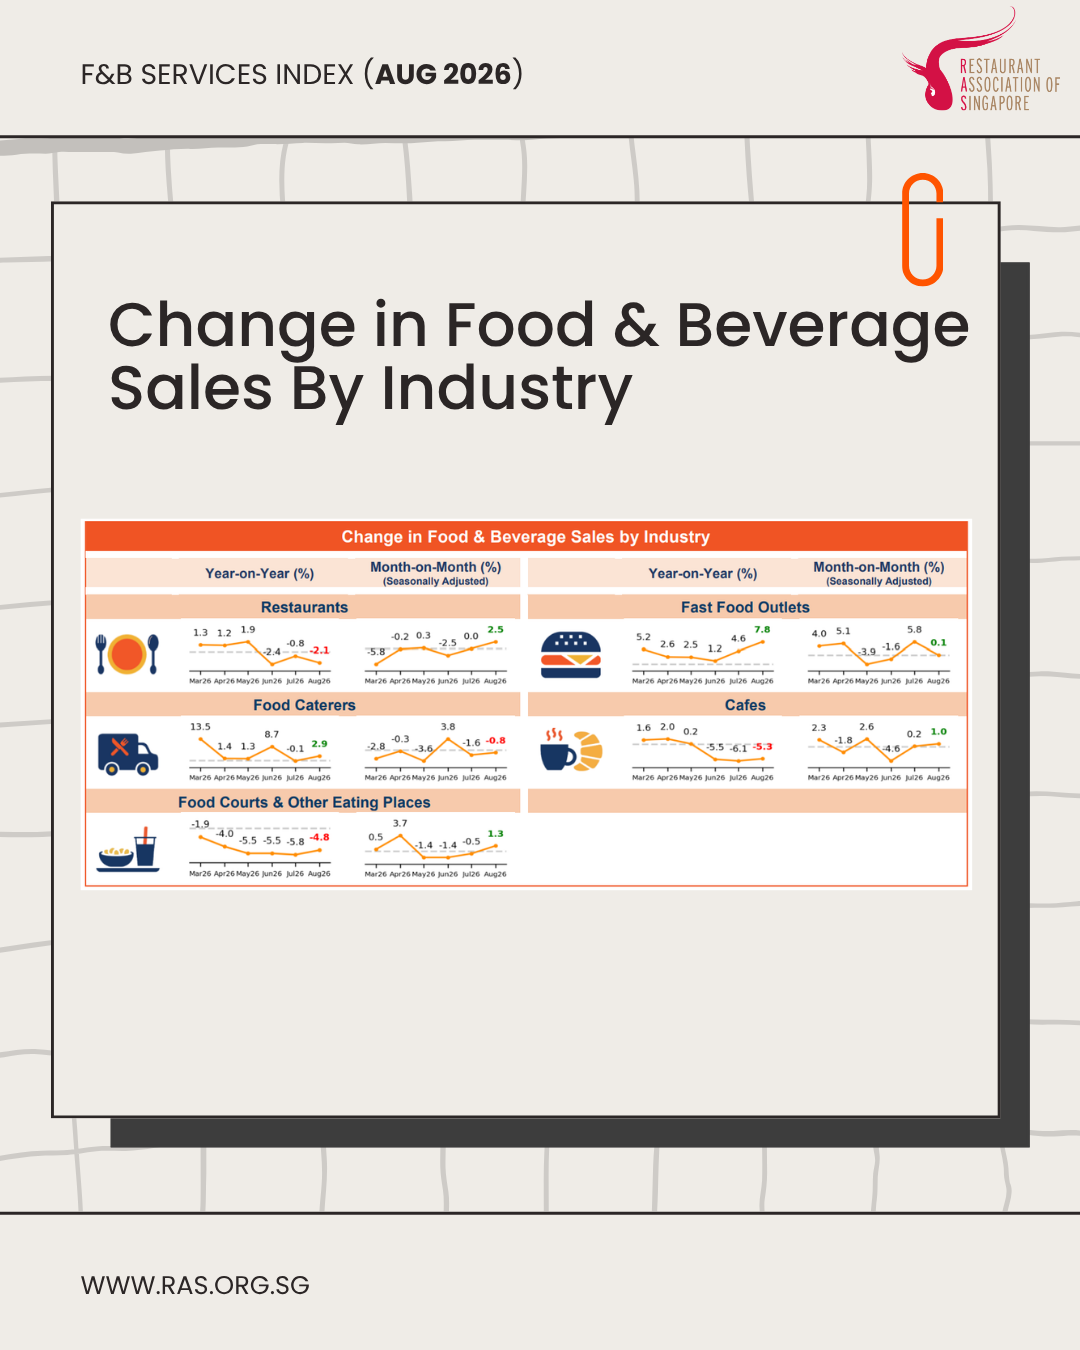
Fast Food Outlets remain the clear leader. Sales rose 7.8% year-on-year, up from 4.6% in July. Month-on-month sales were essentially flat (+0.1%), so fast food held on to the strong gains it made in July. Value and convenience continue to resonate with diners.
Food Caterers returned to growth, with sales up 2.9% year-on-year after a marginal 0.1% dip in July. Month-on-month sales eased 0.8%, so we will need a few more months of data to see whether demand for event and corporate catering is truly firming.
Restaurants sent mixed signals. Year-on-year, the decline deepened to 2.1% from 0.8% in July. Month-on-month, however, restaurants posted the strongest growth of any segment at 2.5%. Diners are coming back month to month, but restaurant sales have not yet returned to last year's levels.
Cafes and Food Courts & Other Eating Places are still the hardest hit, at -5.3% and -4.8% year-on-year respectively. Both declines are narrower than in July (-6.1% and -5.8%), and both segments grew month-on-month (+1.0% and +1.3%). These are early signs of stabilisation in the categories that have been under the most pressure.
The Online Sales Story
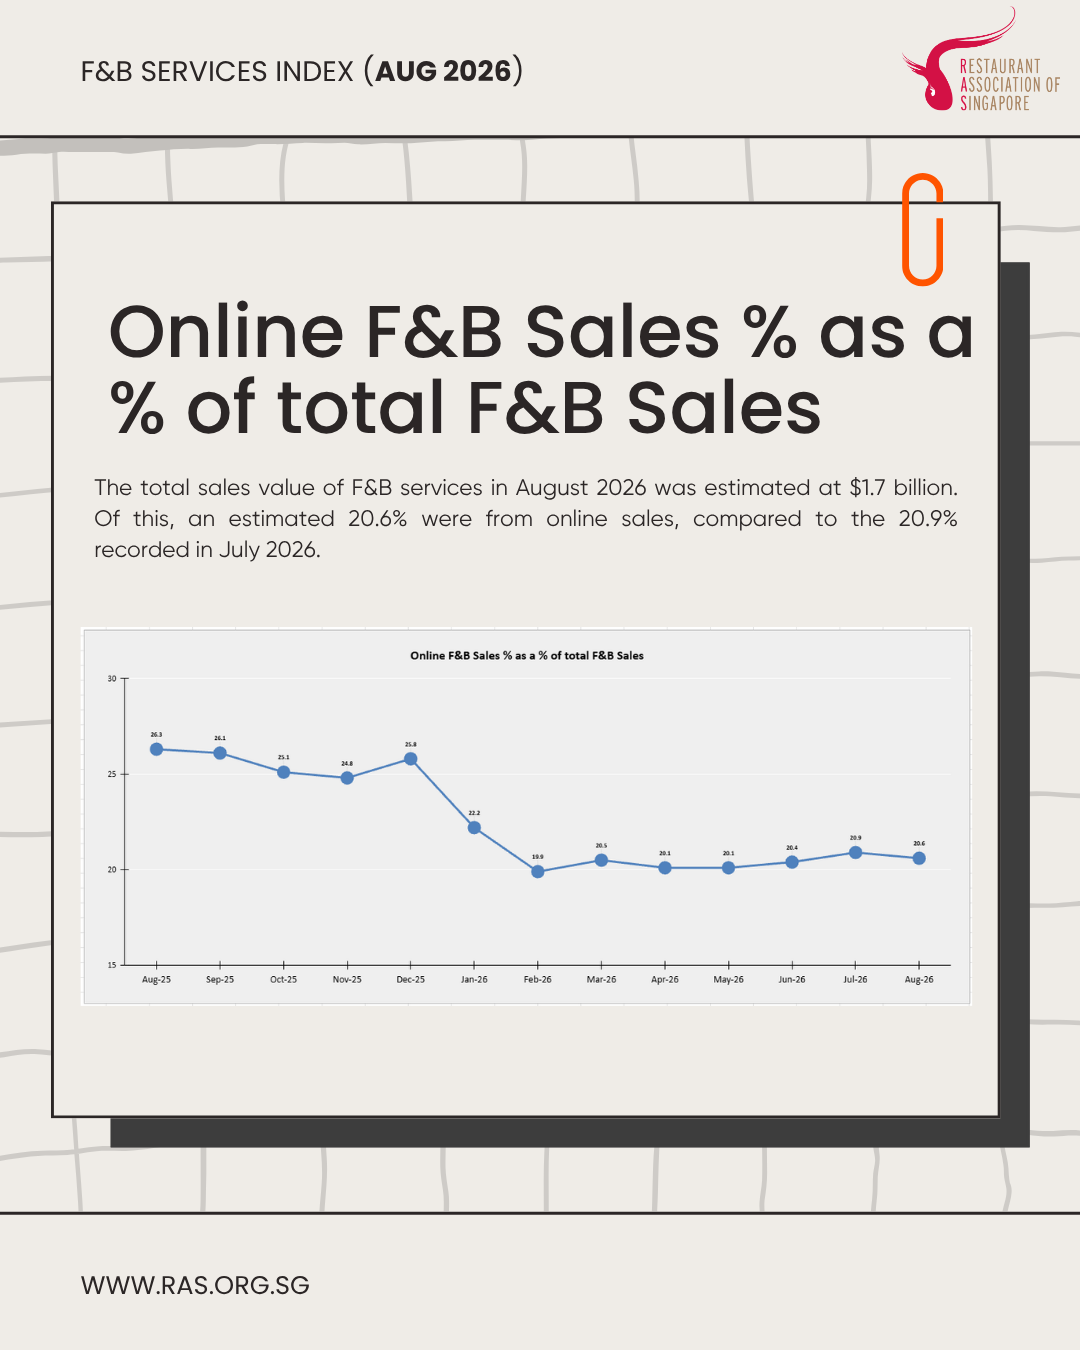
Online orders made up 20.6% of F&B sales in August, little changed from 20.9% in July. Online has held steady at around one-fifth of total sales for several months. For most operators, the question is no longer whether to be on delivery platforms, but how to make those orders profitable.
The Wider Picture
Retail sales excluding motor vehicles rose 1.6% year-on-year in August, while F&B sales fell 1.6%. Consumers are still spending, but spending on dining out has not kept pace. When household budgets are under pressure, discretionary dining tends to be among the first expenses people trim.
It is also worth noting that the index does not cover individual stalls in hawker centres, food courts and coffee shops. The experience of many smaller operators therefore sits outside these figures.
What This Means for Operators
- Value is winning. The strength of fast food and the continued pressure on cafes point to price-conscious diners. Operators should review menu pricing and how clearly their value proposition comes across.
- Watch the middle. Restaurants are seeing customers return month to month but remain below last year's sales. Margin discipline matters more than chasing volume.
- Make online pay. With delivery steady at about a fifth of sales, check your platform commissions, packaging costs and delivery menu pricing.
- Use the support available. Productivity, digitalisation and manpower schemes can help ease cost pressures while demand recovers.
RAS's View
August's figures give some cause for cautious optimism. They do not change the underlying reality: operating costs remain high and demand recovery is uneven. RAS continues to work with government partners on measures that improve cost predictability for F&B businesses, including rental, and on stronger support for local F&B brands.